



For businesses operating across the Middle East and North Africa, accepting payments can still mean navigating a maze of local payment methods, card networks, BNPL providers and bank-based instalment systems. A merchant expanding from one country to another can end up managing multiple integrations, commercial agreements and settlement processes simply to give customers familiar ways to pay.
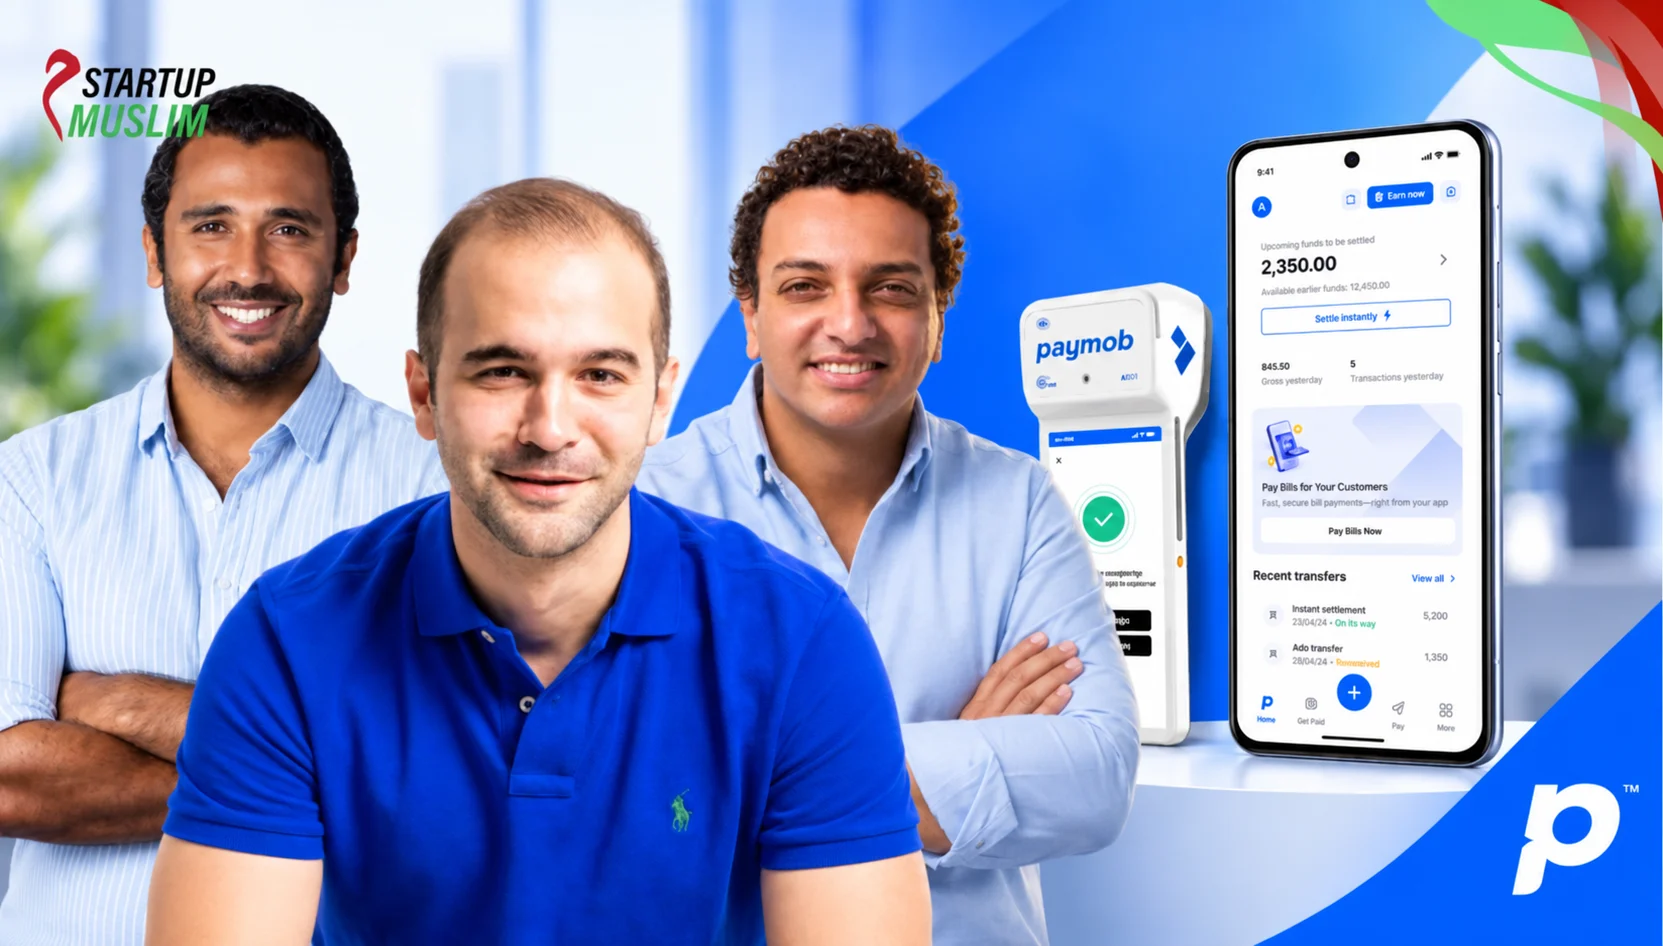
Egypt-founded fintech Paymob is building its business around simplifying that complexity. The payments infrastructure provider has raised $35 million in a pre-Series C round, co-led by Mubadala Investment Company and the European Bank for Reconstruction and Development (EBRD), with participation from British International Investment (BII), Global Ventures and DPI Ventures.
The new capital will support Paymob’s expansion across MENA, while also funding new products for SME merchants and its push into agentic commerce, where AI agents increasingly participate in discovering, selecting and purchasing products and services.
From Egyptian Fintech to Regional Payments Platform
Founded in 2015 by Islam Shawky, Alain El Hajj and Mostafa Menessy, Paymob began with a straightforward proposition: make it easier for businesses to accept digital payments.
Over time, that proposition has expanded into an omnichannel payments platform serving merchants across Egypt, the UAE, Saudi Arabia and Oman. Today, Paymob says its platform serves more than 390,000 merchants and provides access to more than 60 payment methods through a single technology layer.
The company’s evolution reflects a broader shift in MENA’s fintech landscape. As digital commerce expands across the region, merchants increasingly need to support multiple ways of paying, often with significant differences between individual markets.
Paymob’s strategy is to abstract that complexity away from the merchant.
One Integration for a Fragmented Payments Market
The challenge Paymob is addressing is not simply that there are many payment methods. It is that those payment methods can operate through separate systems, commercial relationships and settlement processes.
According to Paymob, merchants operating across MENA typically need seven to eight different payment methods to serve customers effectively. That can mean separate integrations, negotiations and reconciliation processes for each market and payment channel.
Paymob’s platform is designed to reduce that fragmentation through one contract, one API and one dashboard, giving merchants access to more than 60 payment methods.
The platform supports both online and offline payments, allowing businesses to accept transactions, manage their finances and access additional financial technology services through a single infrastructure layer. For smaller merchants in particular, the proposition is about reducing the technical and operational complexity associated with adopting digital payments.
GCC Growth Is Changing the Business
Paymob’s latest funding comes after a period of rapid expansion in the Gulf.
Over the past 18 months, the company says its consolidated revenues have tripled across its four markets, while revenue generated from the GCC has grown sevenfold. Close to half of Paymob’s total revenue now comes from GCC markets.
The company’s expansion accelerated after it secured a Retail Payment Services Licence from the Central Bank of the UAE in January 2025. Since receiving the licence, Paymob says it has onboarded approximately 20,000 merchants across its three GCC markets.
That growth is changing the company’s geographic profile. What began as an Egypt-focused fintech is increasingly becoming a regional payments infrastructure provider, with the Gulf now accounting for a significant share of its revenue.
For Paymob CEO Islam Shawky, that transition is central to the company’s next stage.
“Paymob morphed into a regional platform over the past 18 months, propelled by the exponential growth of our GCC business,” Shawky said. The new funding, he added, will help the company accelerate its MENA expansion and its product roadmap toward becoming a payments platform for agentic commerce.
The Next Merchant Opportunity Is SMEs
While payments acceptance remains at the heart of Paymob’s business, the company is now looking beyond simply processing transactions.
The new capital will be used to develop products specifically tailored to SME merchants. That is significant because small and medium-sized businesses represent a large portion of the region’s commercial economy, but often have fewer resources to manage fragmented financial technology infrastructure.
Paymob’s model gives it an opportunity to build additional financial products around the payment relationship. Once a merchant’s transactions are processed through a common platform, payments data and merchant workflows can potentially support additional tools for managing finances and growing the business.
The company describes this broader mission as helping SMEs execute transactions, manage their finances and grow through a single technology layer.
Its strategy therefore moves from payments acceptance toward becoming a broader operating layer for merchants.
Preparing for the Age of Agentic Commerce
Perhaps the most forward-looking element of Paymob’s new strategy is its focus on agentic commerce.
As AI agents become capable of researching products, comparing options and initiating transactions on behalf of consumers or businesses, the payments infrastructure behind those transactions will need to evolve.
Paymob wants to position itself for that shift before the market fully matures. The company plans to fast-track its product roadmap around agentic commerce, building on its existing infrastructure connecting merchants to multiple payment methods and transaction systems.
This represents a different kind of opportunity from traditional digital payments. Instead of a human shopper selecting a payment method at checkout, future transactions could increasingly involve software agents interacting with merchants, platforms and payment systems.
The infrastructure underneath those interactions will need to be capable of handling different payment methods and markets without forcing every merchant to build those connections independently.
Backed by Regional and Global Investors
The $35 million round brings Mubadala into Paymob’s shareholder base while deepening the company’s relationship with EBRD, which has backed the fintech previously.
Mubadala’s investment reflects its focus on companies contributing to the UAE’s digital economy and regional fintech ecosystem. Ali Eid Al Mheiri, Executive Director of UAE Diversified Assets at Mubadala’s UAE Investments Platform, said Paymob’s scalable payments platform and GCC growth potential aligned with its ambition to support businesses that can expand across the region.
EBRD’s Bruno Lusic described Paymob as building a payments infrastructure layer for MENA’s SME economy, highlighting the company’s role in reducing friction for merchants operating across fragmented markets.
Paymob’s wider investor base includes PayPal Ventures, Kora Capital, Clay Point Capital, FMO, A15, Helios Digital Ventures, Global Ventures and DPI Ventures, alongside its latest investors.
With the new round, Paymob’s total disclosed funding has surpassed $125 million, following its $50 million Series B in 2022 and a $22 million Series B extension led by EBRD in 2024.
From Payments Processor to MENA Financial Infrastructure
The trajectory of Paymob reflects how the region’s fintech opportunity is evolving.
The first challenge was getting businesses online and enabling them to accept digital payments. The next challenge is connecting fragmented payment ecosystems across countries, giving SMEs more financial tools and reducing the complexity of operating across markets.
Paymob is now adding another layer to that ambition: preparing the infrastructure for a world in which AI agents increasingly participate in commerce.
The company’s next phase will therefore be defined not only by how many merchants it serves, but by how much of the financial infrastructure around those merchants it can simplify.
From its Egyptian beginnings in 2015 to a platform serving hundreds of thousands of merchants across four MENA markets, Paymob is betting that the future of regional commerce will require payments to become less fragmented, more intelligent and increasingly invisible.
And as the company expands across the GCC and beyond, its biggest opportunity may be to make the complexity of MENA payments something merchants no longer have to think about.


